The Best Week Since August. Nvidia, Bitcoin and Housing Paid for It.
The S&P 500 rose 2.5%, its first up week in five. In the same five days Nvidia lost its chief and about 13%, Bitcoin lost 12% and the 10-year yield climbed from 4.86% to 5.15%. The number for next week is 7,654 on the S&P 500.
| Inflow | Oil, groceries and the average stock. Energy led every sector for the week. On Friday staples led, and 314 S&P 500 members rose while the index fell. |
| Outflow | Anything priced off a mortgage rate. A homebuilder, a title insurer and a net-lease landlord were shorts on our board as the 10-year went through 5%. |
| Outflow | Nvidia and Bitcoin. Jensen Huang resigned on Thursday. Bitcoin fell to about $64,500. |
| Watch | S&P 500 at 7,654. Two rallies were sold right at that line this week. A four-hour close over it is the turn. |
| Next | Nvidia reports Tuesday. Its first results without Huang, the same day as October retail sales. |
October consumer prices rose 0.4% against 0.3% expected, and a December rate rise went from likely to priced as certain. Nvidia’s board opened a probe of Jensen Huang on Monday and he resigned on Thursday, with finance chief Colette Kress as interim CEO. The S&P 500 still closed Friday at 7,561.67, up 2.5% on the week, the Nasdaq up 2.3% and the Dow up 2.1%.
- Yields The 10-year closed Friday at 5.15%, up from 4.86% a week earlier. The 20-year sits at 5.52%.
- Crypto Bitcoin fell about 12% over five days to roughly $64,500, and Ether about 12% to $1,800.
- Gold Down about 3.6% on the week to $3,886. When cash pays 5%, metal that pays nothing gets sold too.
The week read −4, −4, −3, −7, −2 from Monday to Friday. Thursday’s drop is when the money light went out, and it stayed out. Strength recovered by Friday but all three lights are still dark, which is a bounce, not a turn. Fear at 17 says nobody is panicking. Bonds and stocks are not moving together, so this is selling, not a stress event.
Last week the money left the AI build-out for the physical economy. This week it kept going. Energy led all eleven sectors. On Friday, with the Nasdaq down 0.9%, staples led and 314 of the S&P 500’s members rose against 185 that fell. The equal-weight index beat the normal one. When most stocks rise and the index falls, the index is carrying a few large problems, and this week the problem had a name.
| Day | Where the money went first |
|---|---|
| Wednesday | AI rallied without Nvidia. CoreWeave rose 25% on a beat and a raised forecast. |
| Thursday | Huang resigned. AMD and Broadcom each rose about 6% while Nvidia fell 4.3%. The money left the company and went straight to its rivals. |
| Friday | The rivals were sold too. AMD, Dell and Broadcom led the losers, and staples, energy and banks took the money. |
That sequence is the point. The rivals were the first receivers of the Nvidia money for exactly one day. By Friday it had left chips altogether.
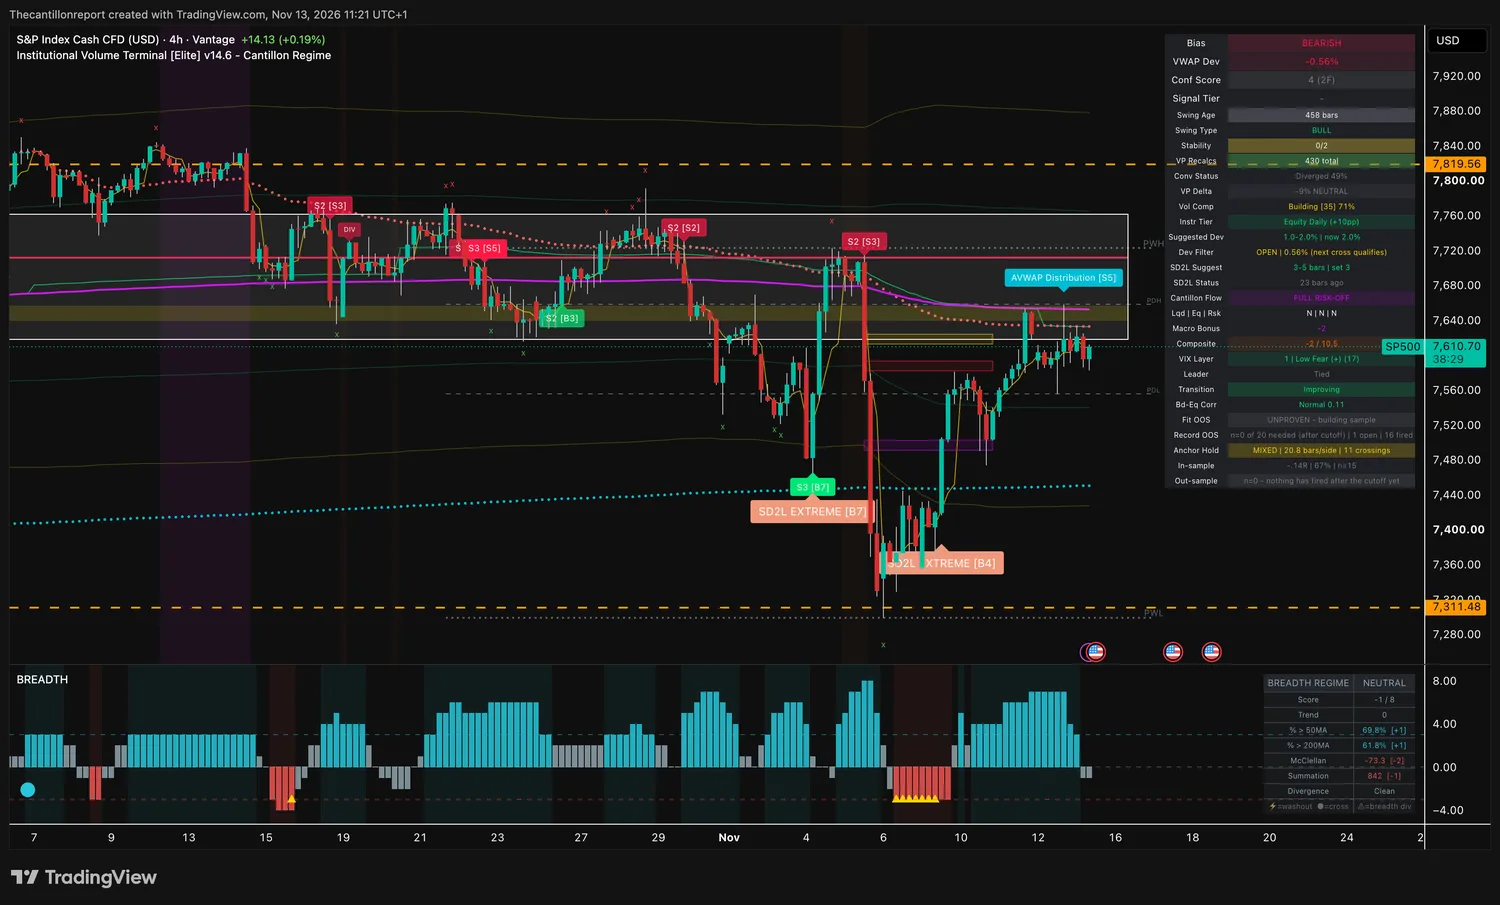
Last week the S&P 500 fell out of a two-month box and hit an oversold extreme at 7,311. This week it bounced straight back to the price large money paid over the swing, and it was sold there twice.
| Reading | What it says |
|---|---|
| Inside the window | Friday morning the index sat 0.56% under its line, close enough that the next cross counts. Last week it was 3.85% under. |
| A sell mark at the line | The terminal printed a distribution label right at 7,654. That is large money selling into the rally, not buying it. |
| Friday’s close | The cash index closed at 7,561.67, right on Thursday’s low area and about 1.2% under the line. |
The number for next week: 7,654 on the S&P 500. A four-hour close over it puts the index back above the price large money paid and takes the pressure off. A third failure there, with Friday already closing on Thursday’s low, puts last week’s 7,300 back in play.
The Cantillon effect runs both ways. New money helps whoever gets it first. Dearer money hurts whoever depends on it most, and this week money got dearer. The 10-year went through 5% on Tuesday after the inflation print and closed the week at 5.15%. Look at what the daily board sold:
| Short on the board | Why rates hit it |
|---|---|
| D.R. Horton | A homebuilder. Its buyers borrow at mortgage rates. |
| First American | Title insurance. It earns when homes change hands. |
| NetSTREIT | A net-lease landlord, valued like a bond. |
| FirstEnergy | A utility with heavy borrowing and regulated returns. |
The rest of the line was the assets that pay nothing today. Bitcoin lost about 12%. Gold lost 3.6%. Long Treasuries lost close to 2%. Nvidia lost about 13% on the week and closed Friday near $163, back under the $165 floor it had retaken on Thursday. Friday’s free board had a half-size bounce trade there, with a rule to get out on a four-hour close under $165.17. That rule was hit.
One honest note on the other side: Meta, our top short, rose 2.9% on Friday. Not every name on the board moved our way.
| Deep dive | The finding |
|---|---|
| Omega Flex | Good product, shrinking margin. No debt and a 5.7% dividend, but sales down four years and tariffs cutting the gross margin from 60% to 52%. |
| Zumiez | Below book, above its profits. No borrowings and half its shares bought back, down 55%. Cheap, or just accurate? |
| Evolution | Growing again, priced for zero. About 12 times operating profit, with 51% of revenue from unregulated markets. |
| Nordic Files | Alfa Laval, Assa Abloy and Epiroc added. Every Nordic File now carries a business quality score, and the hub is ranked by it. |
Get First Receivers every Sunday
One email a week: where the money went first, and who is next. Built from the same work as the daily brief.
| When (CET) | What, and why it matters |
|---|---|
| Mon 18:00 | Fed Chair Warsh speaks. With a December rise priced as certain, the question is whether he leaves the door open to half a point. |
| Tue 14:30 | October retail sales, expected flat after 0.8% in September. |
| Tue, after the close | Nvidia third-quarter results. The first call without Huang. |
| Wed 20:00 | Fed minutes, with October housing starts and permits that morning. |
| Our level | S&P 500 7,654. Every new trade stays half size until a light comes back on. |
The daily brief does this every weekday before the US open: which setups to take, where to get in, where to get out, and what size. Friday’s edition is always free. Forward this to one person who trades.
Jesper
Cantillon Research
Index levels and weekly moves are cash-index closes for the week to Friday, November 13, 2026. Yields, commodities, crypto and sector moves come from Bigdata.com market data as of the Friday close. Readings in “Where the market is” and the S&P 500 chart come from the IVT v14.6 terminal on four-hour bars, captured Friday 13 November between 11:18 and 11:25 CET, before the US open; 7,654 is a CFD level and futures will differ. The names listed are the ones published on the daily board during the week, named to show where money moved. They are not new trade calls; entries, exits and size are in the daily brief.
Educational content only. Not financial advice. Past results do not predict future ones.